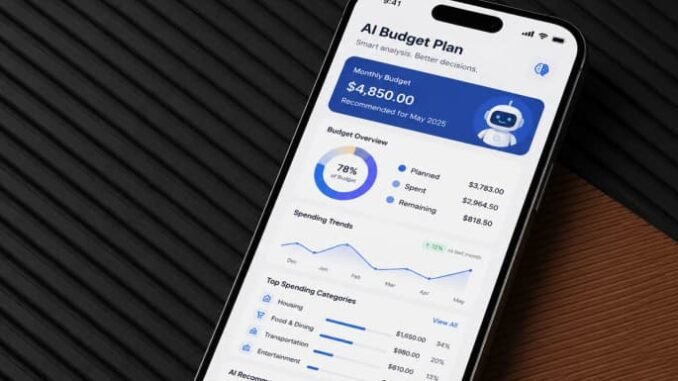
You know you should budget. You know you should track spending, optimize savings, and stop paying full price for subscriptions you forgot about. But between work and life, “managing finances” keeps sliding to next weekend — forever. This is exactly the kind of consistent-but-tedious work AI excels at. If you’re asking how can I use AI to organize my personal finances, here’s the practical playbook: AI as your always-available financial analyst, budget coach, and paperwork assistant. Not as your financial advisor — that distinction matters, and we’ll get to it.
Let’s be clear about what AI can and can’t do here. It can analyze your spending patterns, build budgets, explain financial concepts, compare options, draft difficult money emails, and keep you accountable. It can’t give regulated fiduciary advice, predict markets, or replace a human advisor for complex situations. Used within those bounds, it’s like having a financially literate friend available 24/7 who never judges your DoorDash habit (much).
How Can I Use AI To Organize My Personal Finances? Spending Analysis
Find where your money actually goes
The foundation of every financial plan is knowing your spending — and most people are wrong about theirs by 20–30%. Here’s the AI workflow:
- Export your transactions. Most banks let you download 3–6 months of transactions as CSV. (Use a computer, not your phone, for this.)
- Ask AI to categorize and analyze: “Here are my last 3 months of transactions [paste or upload]. Categorize every transaction, show me monthly totals by category, and flag spending that increased month over month.”
- Ask for insights: “What are my 3 biggest unnecessary spending categories? Where am I leaking money on subscriptions or fees?”
People consistently discover $100–$300/month in forgotten subscriptions, duplicate services, and creeping lifestyle spending. One analysis session — 20 minutes — often pays for itself hundreds of times over. Privacy note: strip account numbers before uploading, and consider using your bank’s built-in categorization tools for the raw data if you’re uncomfortable sharing transactions with AI. Never share full account numbers, passwords, or Social Security numbers with any AI tool.
Build a budget that fits your life
Generic budgeting advice fails because it’s generic. AI builds around your actual numbers:
“I earn $4,200/month after tax. My fixed costs are $2,600 (rent $1,600, car $350, insurance $200, utilities $150, phone $80, subscriptions $220). I want to save $500/month and pay down a $3,000 credit card. Build me a monthly budget with categories, and suggest where to cut.”
Follow up with reality checks: “I tried this last month and overspent on groceries by $150. Adjust.” The iterative conversation — budget, attempt, review, adjust — is what makes it stick. Static budgets die; conversational budgets evolve. For the fundamentals, our guide on creating a budget that actually works covers the principles.
Debt, Savings, and Optimization
Debt payoff strategy
List your debts (balances, rates, minimums) and ask: “Should I use avalanche or snowball for these debts? Show me both payoff timelines and total interest for each.” AI runs the math instantly and explains the tradeoff (avalanche saves money, snowball builds momentum). Then: “Draft a negotiation script for calling my credit card company to request a lower rate.” People who call and ask get rate reductions surprisingly often — but most never call because they don’t know what to say. Now you do.
Savings automation
“I want an emergency fund of $9,000 (3 months of expenses). I can save $400/month. How long will it take, and where should I keep it for the best yield right now?” AI explains high-yield savings accounts (currently 4–5% at online banks vs. 0.01% at big banks — a difference worth hundreds yearly), CDs, and money market options. It can also design a savings challenge or track progress if you check in monthly.
Subscription and bill audits
Paste your recurring charges and ask AI to identify candidates for cancellation, negotiation, or downgrading. Then ask it to draft cancellation-retention-call scripts (“I want to cancel but keep the door open for a discount — what do I say?”). Also powerful: “Compare my current car insurance coverage and price against what’s typical for my profile. What should I ask when shopping for quotes?” For negotiating, our negotiation guide covers the psychology that applies to bills too.
Big Decisions: Thinking Partners, Not Advisors
For major choices — buying a car, evaluating a job offer’s benefits, deciding whether to rent or buy — AI is an excellent thinking partner:
- Scenario modeling: “Compare buying a $25,000 car with a 5-year loan at 7% vs. buying a $12,000 used car with cash. Show total cost of ownership over 5 years including insurance differences.”
- Pros/cons with numbers: “Job A pays $75k with great benefits; Job B pays $85k with minimal benefits. Which is actually better financially?”
- Explaining jargon: “Explain what this 401(k) match formula means in plain English and how much free money I’d leave on the table if I only contribute 3%.”
But: for tax strategy, estate planning, or investment advice involving significant money, consult a qualified human professional — ideally a fiduciary. AI doesn’t know your full picture, isn’t licensed, and isn’t liable if it’s wrong. The Consumer Financial Protection Bureau offers free, unbiased financial education resources worth bookmarking.
Building the Habit: Your Monthly AI Money Date
Tools don’t change finances; habits do. Try this 20-minute monthly ritual:
- Review: Upload the month’s transactions. “Compare this month to last. What changed?”
- Check goals: “Am I on track for my emergency fund / debt payoff / savings goal?”
- One improvement: “What’s the single highest-impact money move I should make this month?”
- Learn one thing: “Explain one investing concept I should understand at my stage.”
Put it on your calendar — the last Sunday of the month, 20 minutes, coffee in hand. People who do a version of this consistently report the same thing: money stops feeling chaotic and starts feeling manageable. Not because AI is magic, but because regular attention is magic, and AI removes every excuse for not paying it.
For related money skills, see our guides on budgeting that works and saving on groceries — often the fastest wins live in the grocery bill.
The bottom line: use AI to analyze your spending (the 20-minute transaction audit), build an adaptive budget, strategize debt payoff, optimize savings placement, and think through big decisions — while keeping sensitive data protected and leaving regulated advice to human fiduciaries. The real power isn’t the AI; it’s the monthly 20-minute habit the AI makes painless. Start with the spending analysis this weekend.
Leave a Reply