My 7-year-old once asked if the ATM “just makes money for free.” I laughed, then realized she’d never seen money as anything but magic — and that was my failure, not hers. If you’re asking how do I teach my kids good money habits early, the good news is that kids are natural learners here. Research shows many core money behaviors are set by age 7. The better news: you don’t need to be a finance expert. You just need to make money visible, give them practice, and model the habits yourself.
The core principle: kids learn money the way they learn language — by immersion and practice, not lectures. An allowance they control teaches more than a hundred talks about budgeting. Here’s the age-by-age playbook.
How Do I Teach My Kids Good Money Habits Early? Start With Visible Money
Ages 3–5: Money exists and it’s finite
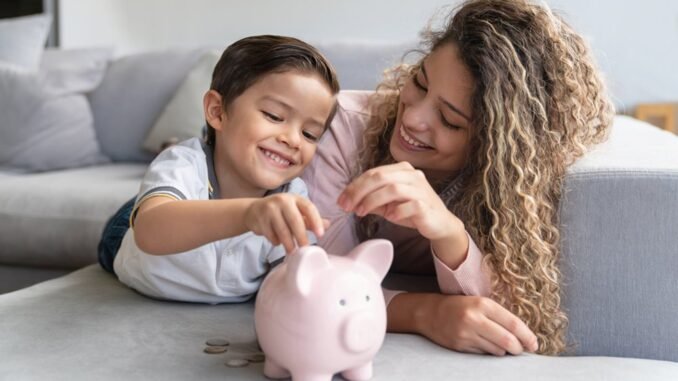
At this age, it’s all concrete. Let them hand cash to the cashier. Play store with real coins. The big lesson: when money is spent, it’s gone — no magic refills. A clear piggy bank (so they can see it grow) beats an opaque one. When they want a toy, practice the phrase “let’s save for it” — delayed gratification starts here, in tiny doses.
Ages 6–9: Earning, dividing, choosing
This is prime allowance age. The system that works best: a small weekly allowance tied to family contributions (not pay-per-chore — you don’t want kids negotiating the price of clearing the table), plus optional extra chores for extra pay. Then introduce the 3-jar method: Spend, Save, Give. Every dollar gets divided — say 70/20/10 — and the jars make abstract concepts physical.
Let them make small spending mistakes. The $8 toy that breaks in a day teaches more than any lecture about “wasting money” — and it’s a cheap lesson at 8. Resist the urge to rescue; a blown allowance is the curriculum. This is also the age to open the “bank of mom and dad”: offer 10% “interest” on savings jar money monthly to demonstrate compound growth in a way kids can feel.
Ages 10–13: Budgeting and comparison shopping
Give them real responsibility: a clothing budget for the school year, or the grocery budget for one family dinner a week (with grocery-saving strategies as their toolkit). Let them comparison shop, check unit prices, and feel the tradeoff: “You can have the brand-name shoes or the shoes plus two shirts.” Introduce the concept of hourly cost: “That $60 game is 6 hours of work at $10/hour — still want it?” This reframes spending instantly.
Ages 14–18: Real accounts, real stakes
Open a teen checking account (most major banks offer free ones with parental oversight) and a custodial Roth IRA if they have earned income — even $500 invested at 16 becomes meaningful by retirement, and the lesson about investing early is priceless. Let them manage a real budget category: gas money, their phone bill portion, entertainment. And talk openly about your own money — the salary conversation, what the mortgage costs, what you save. Kids who grow up with money transparency don’t inherit money anxiety.
The Habits That Matter Most (For Any Age)
- Model it. Kids copy what you do, not what you say. If you impulse-buy daily but lecture about saving, they learn impulse-buying. Narrate your good decisions out loud: “I’m going to wait 30 days on that — it’s on my list.”
- Make giving normal. The Give jar isn’t charity theater — it’s building the identity of someone who shares. Let them choose the cause.
- Talk about advertising. “What is this ad trying to make you feel?” Media literacy is money literacy now. Kids who see through marketing save thousands over a lifetime.
- Celebrate saving milestones. When the Save jar hits its goal, make it an event. Saving should feel like winning, not deprivation.
- Don’t use money as punishment or love. Docking allowance for behavior tangles money with emotions. And “we can’t afford it” said constantly breeds scarcity fear — try “that’s not in our plan right now” instead.
Tools That Help
Greenlight and GoHenry ($5–$10/month) give kids debit cards with parental controls and chore tracking — great training wheels for digital money. For teens, a custodial account at your own bank keeps it simple. Books: “A Chair for My Mother” (ages 4–8), “Alexander, Who Used to Be Rich Last Sunday” (ages 6–10), and “The Teen Investor” for older kids. And the CFPB’s Money As You Grow site has excellent free age-by-age activities.
The Family Money Meeting (15 Minutes, Once a Month)
Here’s the advanced move most parents skip: a monthly family money meeting. Fifteen minutes, same day each month, everyone present — including the kids. The agenda is simple: celebrate (who hit a savings goal? what did the family afford together?), review (one interesting number from the month — “we spent $X on takeout, what do we think?”), and preview (any big expenses coming? a birthday, a trip, school supplies?).
For young kids, keep it visual — a chart of the family savings goal with a fill-in bar they color. For tweens and teens, give them a real voice: let them weigh in on trade-offs (“if we skip eating out twice, we can afford the camping trip”). This does three powerful things: it normalizes money talk (killing the taboo that breeds adult money anxiety), it teaches opportunity cost in real family decisions, and it makes kids stakeholders instead of bystanders. Start this month — order pizza, keep it to 15 minutes, end on the celebration. Paired with a solid family budgeting system, the money meeting turns abstract lessons into lived experience. Your kids won’t remember the lectures; they’ll remember the meetings.
The Bottom Line
Teaching kids money habits early comes down to: make money visible, give them real practice with real (small) stakes, let them make cheap mistakes, and model the behavior yourself. Start this week with the 3-jar method and one honest money conversation. The habits they build before 18 will quietly compound for the next 60 years — that’s the highest-return investment you’ll ever make.
Leave a Reply