What is the difference between an LLC and a sole proprietorship? This is the first big decision every new business owner faces, and the internet makes it sound more complicated than it is. I have operated as both, and here is the short version: a sole proprietorship is free and simple but offers zero liability protection, while an LLC costs $50-$500 to form and legally separates your personal assets from your business. For most people, the right choice depends on risk, revenue, and growth plans.
What Is the Difference Between an LLC and a Sole Proprietorship? Side by Side
- Formation: Sole proprietorship = nothing to file (you are one by default when you start selling). LLC = file Articles of Organization with your state ($35-$500).
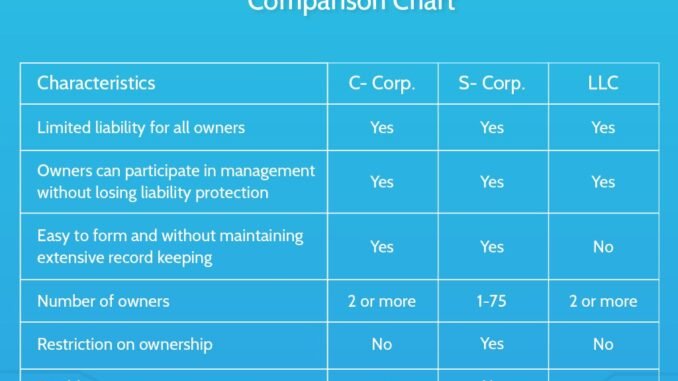
- Liability protection: Sole proprietorship = none. You and the business are legally the same; business debts and lawsuits can take your house, car, and savings. LLC = limited liability. Creditors generally cannot touch personal assets for business debts (with exceptions below).
- Taxes: Nearly identical by default. Both are pass-through: profits are taxed once on your personal return, and both pay self-employment tax (15.3%). An LLC does not save taxes by itself. (LLCs can elect S-corp taxation for savings at higher incomes; sole proprietorships cannot.)
- Ongoing paperwork: Sole proprietorship = essentially none. LLC = annual reports/fees in most states ($0-$800/year depending on state).
- Credibility: LLC looks more professional to clients, partners, and lenders. “Smith Consulting LLC” opens doors “John Smith” sometimes does not.
- Raising money/partners: LLCs can add members and split ownership cleanly. Sole proprietorships cannot take on partners (that makes it a partnership, legally).
When a Sole Proprietorship Is Fine
- You are testing an idea with minimal revenue and want zero overhead.
- Your business has very low liability risk: freelance writing, graphic design, virtual assistance, digital products.
- You have no employees, no physical location, no debt.
- You plan to convert to an LLC later once revenue justifies it. This is a completely legitimate strategy; many successful businesses started exactly this way.
Even as a sole proprietor, protect yourself: get a DBA (“doing business as”) if operating under a trade name ($25-$100, lets you open a business bank account), keep business finances separate, and consider liability insurance ($300-$500/year), which protects sole proprietors too.
When You Need an LLC
- Any physical risk: Food businesses, fitness training, childcare, home services, anything where someone could get hurt or property damaged.
- Employees: Employment liability alone justifies the LLC.
- Significant revenue or assets: Once real money flows, protect it. The $100-$200 formation cost is trivial insurance.
- Business debt or leases: Signing a commercial lease or taking loans as an LLC shields your personal assets.
- Partners: Multi-owner businesses need the LLC’s operating agreement defining ownership and exits.
- Client requirements: Some corporate clients and government contracts require vendors to be LLCs or corporations.
What an LLC Does NOT Protect You From
Important limits people miss:
- Your own negligence or misconduct. You are personally liable for your own wrongful acts regardless of structure.
- Personal guarantees. If you personally guarantee a business loan or lease (common for small businesses), the LLC will not shield you from that obligation.
- Taxes and payroll obligations. Unpaid payroll taxes pierce through to owners personally.
- Commingling funds. Mixing personal and business money can “pierce the corporate veil,” destroying your protection. Separate bank accounts are mandatory, not optional.
The Tax Nuance Worth Knowing
By default, both structures face the same taxes. But an LLC can elect S-corporation taxation once profits are consistently above ~$50,000-$60,000/year. As an S-corp, you pay yourself a reasonable salary (subject to payroll tax) and take remaining profits as distributions (not subject to self-employment tax). This commonly saves $5,000-$10,000+/year at six-figure profits. A sole proprietorship cannot do this. If you expect to grow, the LLC preserves this option.
The Decision Framework
- Just starting, low risk, low revenue? Sole proprietorship. Start earning, convert later.
- Physical risk, employees, partners, or real revenue? LLC now.
- Unsure? The LLC costs $50-$200 in most states. When in doubt, the protection is worth the price of a nice dinner.
- Either way: Separate bank account from day one, track everything, and revisit the decision yearly as the business grows.
The SBA’s business structure guide covers these options plus corporations and partnerships with state-specific details, and it is worth 15 minutes of your time before deciding.
The Bottom Line
An LLC and a sole proprietorship are taxed almost identically, but differ crucially on liability: sole proprietorships offer zero separation between you and the business, while LLCs shield personal assets for $35-$500 plus modest annual fees. Start as a sole proprietorship for low-risk testing, form an LLC when you have real revenue, physical risk, employees, or partners, and keep business money separate under either structure. The LLC’s S-corp election option is a valuable future tax tool worth preserving.
Quick Answers to Common Questions
Can I switch from sole proprietorship to LLC later?
Yes, easily and commonly. Form the LLC with your state, get a new EIN, update your business bank account, licenses, and contracts to the LLC name. There is no penalty for starting simple and upgrading. Many advisors recommend exactly this path: validate the business as a sole proprietor, form the LLC when revenue or risk justifies it.
Does an LLC protect my personal assets from all business debts?
No, with important exceptions: personal guarantees on loans or leases bypass the LLC, your own negligence or misconduct is personally actionable, unpaid payroll taxes pierce through to owners, and commingling personal and business funds can destroy protection entirely (“piercing the corporate veil”). The LLC is strong protection for ordinary business liabilities, not a magic shield against everything.
Which is better for taxes: LLC or S-corp?
They are not alternatives; an LLC can elect S-corp taxation. By default both LLCs and sole proprietorships face identical pass-through taxation including 15.3% self-employment tax. The S-corp election (available to LLCs) saves money once profits consistently exceed roughly $50,000-$60,000/year by splitting income between salary and distributions. Below that threshold, the extra payroll complexity usually is not worth it.
Do I need a separate tax return for my LLC?
Single-member LLCs: no, income reports on your personal return via Schedule C (or Schedule E for rentals). Multi-member LLCs: yes, the LLC files a partnership return (Form 1065) and issues K-1s to members. LLCs electing S-corp or C-corp taxation file corporate returns. The default single-member case adds no tax filing complexity beyond what sole proprietors already handle.
Leave a Reply